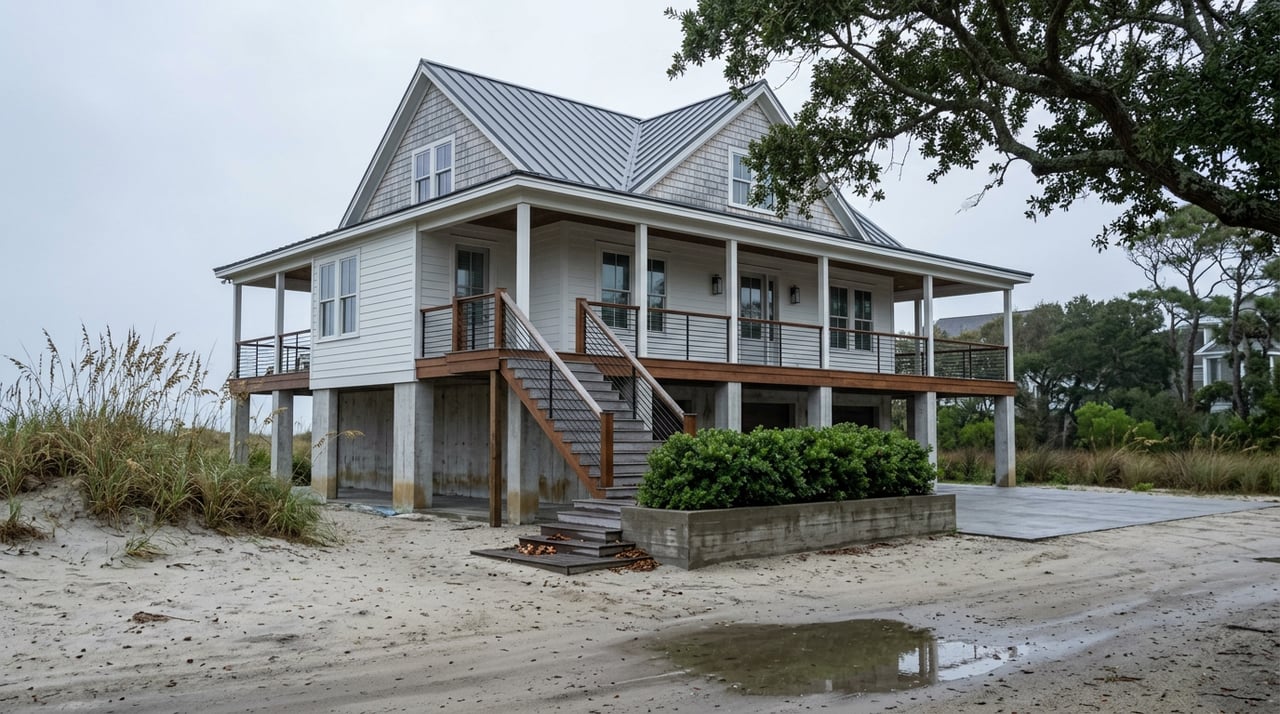
Wrightsville Beach Real Estate Market 2026 Insights
September 3, 2026
September 3, 2026
"Today's luxury buyers are prioritizing stability and long-term value over speculation," Coldwell Banker Sea Coast Advantage's Jessica Riffle Edwards told Wrightsville Beach Magazine this spring, describing a market that has become more discerning after a few frenzied years. That word, discerning, is doing more work than it sounds like it should. A buyer comparing Wrightsville Beach to Landfall or a mainland Wilmington neighborhood on price alone leaves out insurance and renovation considerations. They are reading a number that was never built to answer the question they're asking.
One number worth checking before making an offer is the average annual homeowners insurance cost for ZIP code 28480, which is Wrightsville Beach: as of June 2026, it is $9,688, the highest of any ZIP code in North Carolina. That figure sits well above the state average of $3,124 and it does not include the additional insurance costs for a coastal home here. The median sale price tells you what the house costs to buy. It tells you almost nothing about what it costs to keep.
Harbor Insurance explains that in North Carolina's 20 coastal counties, including New Hanover, standard homeowners insurance excludes wind and hail damage entirely. A single HO-3 or HO-5 policy will not cover storm wind on a Wrightsville Beach home. That coverage has to be purchased separately, and flood coverage is separate again.
| Policy | What it covers | Where you buy it |
|---|---|---|
| Homeowners (HO-3/HO-5) | Fire, theft, vandalism, non-wind perils | Standard private carrier |
| Wind and hail | Storm wind and hail damage | North Carolina Joint Underwriting Association (NCJUA), since private carriers exclude wind in coastal counties |
| Flood | Storm surge, sound-side flooding, heavy rainfall | NFIP or a private flood carrier |
The NCJUA piece has its own quirk worth knowing before you write an offer: its deductibles are percentage-based, not flat dollar amounts. A home insured for $800,000 with a 2% wind deductible carries a $16,000 out-of-pocket obligation before that policy pays a claim, and 3%, 4%, and even 5% deductibles are common in higher-risk coastal locations.
Those three premiums are also climbing on a schedule you can check today. North Carolina Insurance Commissioner Mike Causey settled a rate dispute with the state's Rate Bureau in January 2025 after the Bureau had originally asked for an average 42.2% statewide increase, with proposed hikes as high as 99.4% in some coastal areas. The negotiated settlement phased in a statewide average increase of about 15% over two years, split into a 7.5% bump on June 1, 2025 and another 7.5% on June 1, 2026. Beach territories in New Hanover, Pender, Onslow, Carteret, and Brunswick counties didn't get the average rate. They got roughly 16% in 2025 and another 15.9% in 2026, two increases whose stated rates add to roughly 32% over two years for the exact territory Wrightsville Beach sits in. That schedule is public record, not a rumor, and it's already priced into what you'll pay on a policy renewal after June 1, 2026.
Here's the part that should change how you read any market snapshot for this island. In the 28480 ZIP code, the three-month window ending in May 2026 put the median sale price at $1.7 million, up 3.2% from the same three months a year earlier, but homes needed an average of 119 days to sell, up from just 11 days over that same window in 2025. A separate snapshot from February 2026 counted only 11 houses for sale island-wide, priced from $225,000 to $6,795,000, with a median of $1,750,000 and an average of 57 days on market. Three different measurements of the same island, three different numbers, all correct, none of them a trend.
The scarcity behind that noise is real and specific. One broker quoted in Wrightsville Beach Magazine's spring 2026 roundup put single-family inventory on the island at roughly 13 homes actively for sale against 35 sales over the prior year, a pool small enough that a single closing moves the average meaningfully. When your entire dataset for a month is a handful of closings, one $9.5 million oceanfront sale, like the listing Ace Cofer of Hardee Hunt & Williams brought to market in March 2026, can swing the median by six figures in either direction. That's not a market behaving erratically. That's arithmetic doing what arithmetic does with a small sample.
Wrightsville Beach Magazine quoted Vance Young, a longtime broker at Wrightsville Beach's own Intracoastal Realty office, describing a version of this that he'd never seen before in his career. "Traditionally as markets slow, they have slowed from the top down, and the bottom remained healthy," he said. "For the first time in my 38-year career, I'm seeing the top remain very healthy while the bottom tier has slowed." That's a bifurcated market wearing one median. High-end oceanfront and soundfront homes keep moving. Everything else has cooled. Average the two together and you get a number that describes neither.
If you're cross-shopping Wrightsville Beach against Landfall, the contrast is instructive. According to Wrightsville Beach Magazine's spring 2026 roundup, Landfall recorded 107 home sales in 2025, with an average sale price above $1.7 million and 49 properties closing above $1 million. Its top sale that year, 1064 Ocean Ridge Drive at $7.75 million, matched Landfall's own record from the year before, listed by Vance Young of Intracoastal Realty and sold by Lisa Sledzik of RE/MAX Essential.
Put those two numbers side by side. Landfall's average sale price and Wrightsville Beach's median sale price land in roughly the same neighborhood, north of $1.6 million. But Landfall generated that number from 107 transactions in a year. Wrightsville Beach generated its comparable figure from roughly 35, spread across a listing pool that rarely exceeds a dozen or so active homes at any moment. A median built on 107 sales is a reasonably stable statistic. A median built on 35 sales pulled from an inventory of 13 is closer to a snapshot of whichever three or four homes happened to close that quarter. The two neighborhoods can share a price point on paper and still deserve completely different levels of trust in what that price point predicts about your own transaction.
Another cost not reflected in the median is what you're allowed to build. The Town of Wrightsville Beach caps residential structure height at 40 feet, measured from the centerline of the street, according to the town's own Planning and Inspections FAQ. If your property sits in an Area of Environmental Concern, which covers most oceanfront lots under the Ocean Erodible Area designation and most soundfront lots under the Estuarine Shoreline designation, any project disturbing more than 200 square feet of ground can require a CAMA Minor Development Permit before work begins.
A few additional triggers are worth knowing if you're eyeing a fixer-upper rather than new construction:
These limits can affect a contractor's bid or whether a permit is granted, so review them during due diligence.
The median price for Wrightsville Beach is a real, published, defensible number. It is also the wrong number to plan a purchase around, because the market it describes is too thin and too split between tiers to behave the way a median from a deeper market would. Before you compare a Wrightsville Beach listing to anything inland or in a larger community like Landfall, get quotes on all three insurance policies, not just homeowners, since wind and flood premiums can add thousands to ownership costs. Ask whether the parcel sits in an AEC and pull its permit history from the town's own map before you assume a renovation is straightforward. And when you're sizing up the market itself, look at rolling 90-day comps instead of the trailing annual median. On an island where 13 homes and 35 sales can define an entire year, that's the only version of the number that tells you something true.
If you're weighing Wrightsville Beach against Landfall, Mayfaire, or a mainland Wilmington neighborhood and want someone to run the real comparison, not just the list price, Rainey Wallace can walk through the insurance stack, the permit history, and the actual comps for the specific home you're considering. Let's Connect.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.
Offering clients unmatched regional expertise, global network strength, and proven results. For a real estate experience driven by professionalism, clarity, and results, contact Rainey!
RAINEY WALLACE
1900 Eastwood Rd Ste 38 Wilmington, NC 28403